If you are thinking of getting a renovation loan in Singapore to renovate your new home, this is the post that you are looking for! In this post, I will provide you with some general information about getting a renovation loan and what to look out for. After reading this post, you will at least know what you are getting into before signing on the dotted line. Plus I have a special renovation loan deal for you!
What is the lowest interest rate for renovation loan?
At the moment, 14 September 2013, from the research I have done, the lowest interest rate is 2.88% per annum (flat rate) with a minimum of $15,000 loan. At the moment, there is no indication when the 2.88% interest rate will end.
**Please leave me a comment below if you managed to find a bank that offer even better interest rate.
Is there any other charges?
There is a 1% processing fee. For some banks, you have the option to pay cash, while the others will deduct this fee directly from the loan amount, for example $15,000 – $150 = $14,850.
Difference between flat and variable rate
The banks offered 2 types of renovation loan. One is flat and the other is variable rate. Flat rate is for customers who are comfortable with just paying the same amount of instalment every month. Variable rate is for customers who plans to do early repayment (only 2% penalty fee on prepaid amount).
What does it means: If you are comfortable with knowing how much to pay per month, use flat rate. Most homeowners will use flat rate in normal situations. Variable rate is for homeowners with high cash flow or liquidity who wants to repay the loan really early. However, because of some unknown variable factor, it is rare that anyone will take up the variable rate.
Summary of loan repayment amount and interest rate
Most banks like to show percentages which are very small numbers. But these small figures can add up to a sizeable sum. It is important to understand what you are going into before committing yourself. Therefore, I have came up with a few tables that will give you a clearer view of what you are going into with one of the (or the) lowest interest rate renovation loan in town.
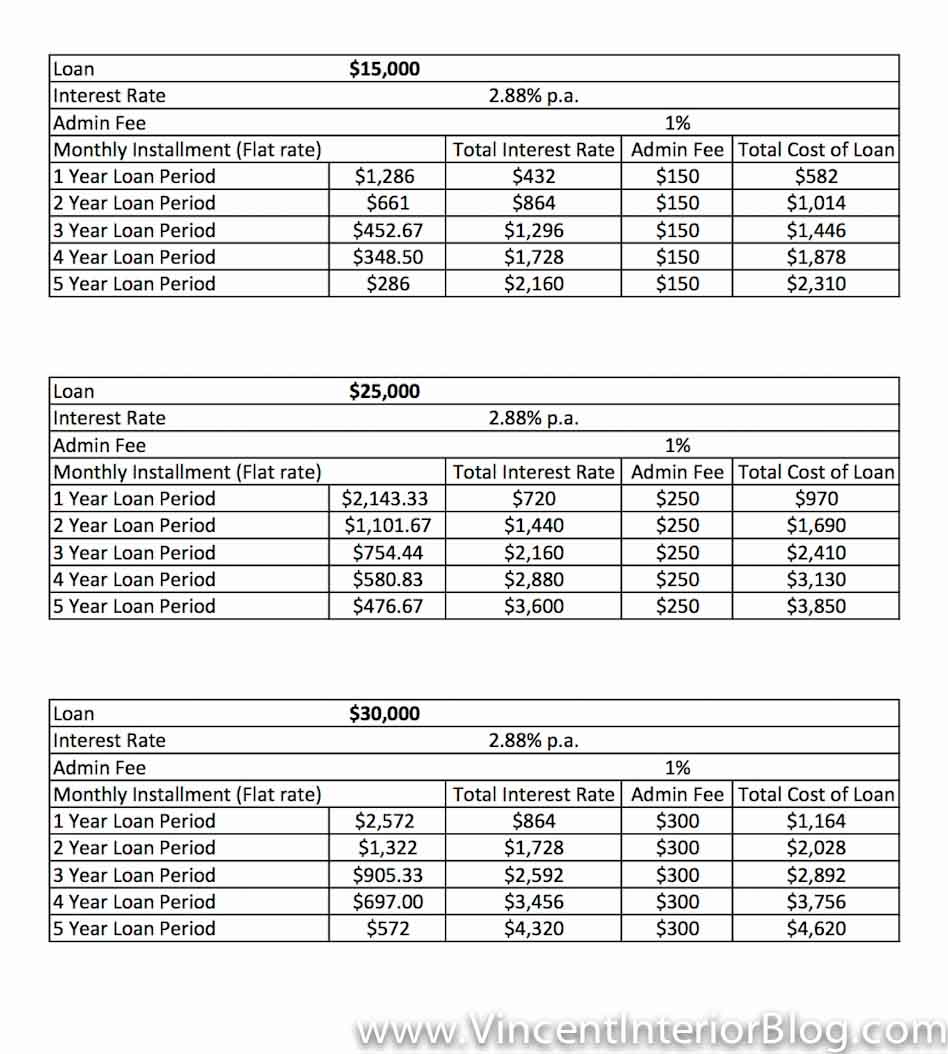
**The above estimated figures might defer slightly from actual situation. You can also use the bank’s calculator to work out the monthly loan instalment figure (Please note: interest rate is 2.98% in the calculator).
What does the table means to you? Nothing is for free. When you borrow more money or get a longer loan period, you pay more interest. If you want to pay lower monthly instalment, you need to get a longer loan period.
What are the penalties and other charges involved?
- Late payment fee: 10.7% (5%+5.7% Prime Lending Rate) based only on the instalment overdue
- Default payment penalty: 10.7% (5%+5.7% Prime Lending Rate)
- Early repayment fee: 2% penalty fee on prepaid amount
- Cancellation fee: 1% on the loan amount cancelled (maximum $200)
- Disbursement fee: Free 1st Cashier’s Order for disbursement to your contractor and $10 each for subsequent Cashier’s Orders (Max. 3)
Advises from the banker (from the loan department)
- Every individual cases differ from each other. Owners should only apply for the installment package that they are comfortable with in case they need cash for emergency uses and unable to pay, leading to additional late payment.
- Upon loan approval, cashiers’ order (payable to the contractor firm), should be passed to home owners first so they will pass to the contractors personally.
- There are more and more young couples getting properties and want to do up their house. However their commitment level are too high (e.g. too many credit cards, bank o/d and loans with many other banks). This will make it tough for any banks to approve such loans. Therefore, only customers with neat and good credit profile will be more likely to get the loan approved. If not, they will need to bring in joint borrowers (someone related e.g. parents, spouse or siblings) or guarantors (friends, neighbours etc.)
How much can you borrow?
Renovation Loan: 6 X of monthly income or $30,000 whichever is lower of a single application.
Procedures for applying for RHB renovation loans and lead time
Eligibility
– Main Applicant:
- Singapore Citizen or Singapore Permanent Resident
- Aged between 21 to 55 years
- Earning a minimum annual income of S*$24,000*
– For the Joint Applicant (where applicable):
- Singapore Citizen or Singapore Permanent Resident
- Aged between 21 to 55 years
- Must be a spouse, sibling, parent or child of the Main Applicant
- Gainfully employed
Homeowners would have to provide the following documents for renovation loan application:
- Photocopy of NRIC (both sides) of Applicant(s)
- Proof of Income:
Salaried Person:
- Latest 3 months Pay Slip AND (ii) CPF Statement for past 6 months OR (ii) Latest Income Tax Notice of Assessment (NOA)
Self-Employed:
- Latest Income Tax Notice of Assessment (NOA) for the past 2 years
*for free NOA, log on and print from http://mytax.iras.gov.sg using SingPass or IRAS PIN
- Copy of Contractor’s Quotation / Invoice duly signed by BOTH applicant(s) and Contractor(s). Full address including postal code of property to be renovated is required as well.
- Proof of ownership on property to be renovated e.g. HDB Letter of Approval / Flat Information, CPF Property Withdrawal Statement, Certificate of Title, Property Tax bill, etc
- For joint application: Proof of relationship document e.g. copy of marriage or birth certificates
The lead time for the loan approval after completed documents submission is about 3-5 working days for renovation loan.
How do banks approve your renovation loan?
The credit officers actually calculate each applicant’s commitment level by using DSR (debt servicing ratio) of 20%. For your example, since HDB is fully paid by CPF, it will not be considered in the calculation. For example if your income is $5000 and monthly commitment is $2000, your DSR is $2000/$5000 X 100% = 40% which is way over the maximum DSR of 20%. In this case, the credit officers will request for an additional joint (if the main already has a joint) or a guarantor to come in and support this loan application.
Extra benefits or marketing strategies from the banks
Some banks offer:
- free personal accident insurance on the main borrower
- furnishing loan for their renovation loan customers. Interest rate: 6.5%p.a. for 1st year, 7% p.a. for 2nd to 5th year. Furnishing Loan: 4 X of monthly income of main applicant or $20,000 whichever is lower.
- free gifts as one of the way to attract customers.
My personal advice
- Take flat rate because you need your financial status to be predictable at all times.
- Split the loan amount into 3 cheques so that you will only give your money to the Interior Designer based on work progression. This will also helps to protect yourself from scams. An additional cost of $10 on each cheque is worth it.
- If you need more loan and both your income and your spouse’s income can support it, you can split the application. For example the total renovation fee is $50,000, husband apply $25,000 and wife apply $25,000 loan. Reason is because there is a $30,000 loan amount limit per application.
- Get the loan period that you are comfortable with. Use the monthly loan instalment as a guide.
- Always make sure that you can service the instalment on time without any late penalty.
Special deal for you!
Vincent Interior Blog will give you a free cash on top of what the banks offer if you take up the loan from my referred bankers:
- $20,000 – $29,999 loan amount = $40 Cash
- $30,000 loan amount = $60 Cash
**This is a personal offer that has nothing to do with the banks. Your loan will be from a approved and legal bank in Singapore.
You get all the benefits like everyone else from the bank and additional free cash from Vincent Interior Blog! Absolutely no other stings attached except:
- minimum $20,000 loan amount
- must be from my referred bankers
Fill in the application today:
Free cash gift procedures:
- fill in the application form
- the banker will contact you shortly about application procedures
- after approval, simply take a picture (using your mobile phone) or scan the approval letter and email to vincentinteriorblog@gmail.com.
- After the loan has been given out to your Interior Design, a cheque (with the applicant’s name) will be send to via post.
Tags: RENOVATION LOAN